
A bona fide donation is a gift made freely, out of generosity, with nothing coming back to the donor. SARS puts the test as no quid pro quo, no reciprocal obligations and no personal benefit. If you receive advertising, goods, a ticket or any other benefit in exchange, it is not a Section 18A donation — usually it is sponsorship, which is taxed differently.
At a glance — as of October 2026
- SARS’s test
- A gratuitous disposal by the donor, out of liberality or generosity
- What disqualifies it
- Any quid pro quo, reciprocal obligation or personal benefit for the donor
- What can qualify
- Cash, or property in kind, paid or transferred to an approved organisation
- What SARS lists as not a donation
- Donated services, event tickets, auction bids, raffle tickets, school fees
- Sponsorship instead
- Tested under section 11(a) as a business expense, not under section 18A
- Claiming an invalid receipt
- The deduction is disallowed, and penalties can follow
What does ‘bona fide’ mean for a Section 18A donation?
It means a real gift. SARS’s own Section 18A training material, dated 5 October 2023, defines a valid (bona fide) donation as a gratuitous disposal by the donor out of liberality or generosity. The donor gives something up and expects nothing for it.
The same slide spells out the reverse: no quid pro quo, no reciprocal obligations and no personal benefit for the donor. The material adds that a donation must not have any conditions attached for personal benefit.
Section 18A itself is built on this word. SARS’s Binding General Ruling 71 describes the deduction as covering the sum of any bona fide donations in cash or of property made in kind, actually paid or transferred to an approved organisation during the year of assessment.
What turns a donation into sponsorship?
Anything flowing back to the donor. Our Section 18A page puts it in one line: if you receive goods, services, advertising value or any other benefit in exchange, it stops being a donation for section 18A purposes and becomes something else — sponsorship, usually.
In practice the line is crossed by the deal, not the label. Logo placement, naming rights, hospitality, tickets or product exposure are all value returned. Calling the payment a donation in an email does not change what was exchanged.
Equally, a donation does not become sponsorship because it is designated to a purpose. A gift can be ring-fenced to a specific programme and reported against, as our Section 18A page notes, provided the donation itself stays bona fide.
How is sponsorship taxed differently?
Sponsorship is not claimed under section 18A at all. It is tested as an ordinary business expense under section 11(a) of the Income Tax Act: spent in the production of income, and not capital in nature.
That test cuts the other way. The Tax Faculty’s May 2024 guidance says a company must show a clear commercial benefit, not just goodwill or social contribution, and that purely philanthropic or public-relations sponsorships are usually not deductible. It describes the area as grey.
| Section 18A donation | Sponsorship | |
|---|---|---|
| What comes back | Nothing — no quid pro quo | Advertising, branding, tickets, goods or another benefit |
| Where it is claimed | Section 18A deduction | Section 11(a), as a business expense |
| What has to be shown | A gift out of generosity, to an approved organisation | Spent in the production of income, with a commercial benefit |
| Ceiling | 10% of taxable income; excess carried forward | Not the section 18A ceiling — the business purpose has to hold |
| Paperwork | A Section 18A receipt from the organisation | Evidence of the commercial return |
Neither route is better or worse in itself. They are different transactions, and the paperwork has to match the one actually taking place. Your accountant decides which applies to your figures; this table is a map, not advice.
What payments does SARS say are not donations?
SARS’s 2023 training material lists non-qualifying donations directly. Each has the same flaw: the payer receives something, or nothing is gratuitously given.
- Donated services, such as a professional rendering a skill free of charge.
- The price of attending a fundraising dinner, dance or charity golf day.
- A winning auction bid for goods auctioned to raise funds.
- Raffle or lottery tickets.
- School fees, admission fees or compulsory school levies.
- Free rent, water and electricity a landlord gives an approved organisation, and payments of a debt due.
Goods are a separate question — property in kind can qualify. See whether you can donate goods instead of cash under Section 18A.
Can part of a payment still be a donation?
Yes, if the two parts are genuinely separate and tracked. In Binding Private Ruling 338, issued on one organisation’s fundraising event, SARS accepted that payments a tracking system identified as donations were bona fide donations under section 18A.
The rest was not. Payments for taking part in event activities were kept off the receipt, because the payer received something for them. Only the portion identified as a donation could be receipted, as Tax Consulting South Africa summarises the ruling.
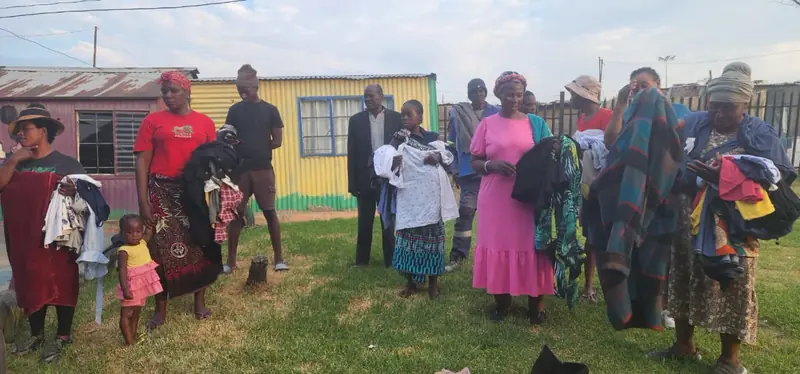
A UDRS blanket and clothing handout in Kya Sand — where a bona fide gift ends up, with nothing routed back to the giver
Why does getting this wrong matter to the donor?
Because the donor carries the loss. SARS’s 2023 material is blunt about a donor claiming an invalid Section 18A receipt: the donation will be disallowed, with appropriate enforcement action such as understatement penalties.
SARS also names receipts issued for incorrect “donations” — fundraising events and services rendered — as something it is working to stop, and says the newer approach places responsibility on both donors and issuing institutions.
That is why our Section 18A page makes a plain commitment: we will tell you which one you are looking at rather than let a certificate be issued that does not hold up. If a proposed arrangement includes branding or another return, raise it with us before the money moves.
Whether a payment is bona fide for Section 18A says nothing about B-BBEE recognition, which is a separate system. See Section 18A versus B-BBEE points.
This page explains the rules as of October 2026. It is not tax advice, and UDRS NPC is not a tax practitioner. Your accountant will apply this against your actual figures.
Key points
- Bona fide means given freely, out of generosity, with nothing coming back.
- Advertising, tickets, goods or any other return make it sponsorship, not a donation.
- Sponsorship is tested under section 11(a) and needs a commercial benefit.
- Claiming an invalid receipt means the deduction is disallowed, and penalties can follow.
Frequently asked questions
What is a bona fide donation under Section 18A?
A gift made freely, out of liberality or generosity, to a Section 18A-approved organisation. SARS describes the test as no quid pro quo, no reciprocal obligations and no personal benefit for the donor. It can be cash or property in kind.
Can we get our logo on something and still claim Section 18A?
Not for that payment. Advertising value is a benefit flowing back to the donor, so the arrangement is usually sponsorship rather than a donation. Sponsorship is tested as a business expense under section 11(a) instead.
Is a charity golf day or fundraising dinner ticket deductible under Section 18A?
No. SARS lists amounts paid for attending a fundraising dinner, dance or charity golf day as non-qualifying, along with winning auction bids and raffle tickets. A separately tracked donation made at the event can still qualify.
Can sponsorship still be tax-deductible?
It may be, but not under section 18A. Sponsorship is tested under section 11(a): it must be spent in the production of income and show a clear commercial benefit. Purely philanthropic or public-relations sponsorship is usually not deductible. Ask your accountant.
Do donated services count as a bona fide donation?
No. SARS lists donated services, such as a professional rendering a skill free of charge, as non-qualifying. Section 18A covers cash and property in kind, not time or skills.
What happens if a donor claims a Section 18A receipt that is not valid?
SARS says the donation will be disallowed, with appropriate enforcement action such as understatement penalties. That is why it pays to settle whether an arrangement is a donation or sponsorship before the money moves.
Not sure which one you are looking at?
UDRS NPC is an approved Public Benefit Organisation, PBO 930091096. Tell us what you have in mind before the money moves, and we will tell you plainly whether it is a donation or sponsorship.
Looking for a commercial partnership instead? Our partners page sets out each track. For what the receipt itself must show, read what changed on Section 18A certificates from 1 March 2026.
Sources
Checked on 30 October 2026:
- Tax Deductible Donations: Basic Principles for S18A Approved Tax Exempt Institutions (SARS, 5 October 2023) — the bona fide test, non-qualifying donations, consequences of an invalid receipt
- Binding General Ruling 71 (SARS, 16 May 2024) — the deduction covers bona fide donations in cash or of property in kind
- Section 18A fact sheet (SARS) — the 10% of taxable income limit and the carry-forward
- One Good Turn: Donations Made at Fundraising Events (Tax Consulting South Africa) — Binding Private Ruling 338, separating donations from event participation
- Sponsorships (The Tax Faculty, 20 May 2024) — section 11(a) and the need for a commercial benefit