From 1 March 2026, Government Notice 6762 replaced SARS's 2023 list of extra details a Section 18A receipt must show. Three things changed: the donor's income tax reference number is no longer "if available", a donation of goods needs an accurate description, and it needs the deemed deduction value under section 18A(3) or (3A).
At a glance — as of September 2026
- The rule
- Government Notice 6762, Government Gazette No. 53589, issued under section 18A(2)(a)(vii) of the Income Tax Act
- Published
- 24 October 2025
- Applies to
- Every Section 18A receipt issued on or after 1 March 2026
- Replaces
- Notice 3082 (Gazette No. 48104, 24 February 2023)
- Genuinely new
- Tax reference number without the "if available" qualifier; description of goods donated; deemed deduction value for goods
- What it does not change
- The 10% of taxable income ceiling, or who may claim
What does Notice 6762 actually say?
It is one page of schedule, signed by the SARS Commissioner, listing the "further information" a Section 18A receipt must carry on top of what the Income Tax Act itself already requires. It states that it replaces Notice 3082 with effect from 1 March 2026 and applies to all receipts issued on or after that date.
The schedule groups the details into three blocks: information about the donor, information about donations of property in kind, and information about the receipt itself. The second block is the one that did not exist before.
What was already required before March 2026?
More than most donors realise. Section 18A(2)(a) of the Act has always required six core items: the organisation's Section 18A reference number, the date the donation was received, the organisation's name and an address for enquiries, the donor's name and address, the amount (or the nature of a non-cash donation), and a certification that the donation will be used exclusively for the organisation's approved purposes.
Since 1 March 2023, Notice 3082 added a second layer — donor type, identification details, contact details and a unique receipt number. Notice 6762 keeps that layer and edits it. The table sets the two notices side by side, using each notice's own wording.
| Detail on the receipt | Notice 3082 (1 Mar 2023 – 28 Feb 2026) | Notice 6762 (from 1 Mar 2026) |
|---|---|---|
| Nature of the donor (natural person, company, trust, etc.) | Required | Required |
| Identification type and country of issue (natural person) | Required | Required |
| Identification or registration number | Required ("of the donor") | Required ("in the case of a juristic person") |
| Trading name, if different from the registered name | Required | Required |
| Donor's income tax reference number | Required "if available" | Required — qualifier removed |
| Donor's contact number | Required | Required |
| Donor's email address | Required | Required |
| Unique receipt number | Required | Required |
| Adequate and accurate description of property donated in kind | Not listed | New |
| Deemed deduction amount for property in kind, under s18A(3) or (3A) | Not listed | New |
So several articles describing a "unique serial number" or an email field as new in 2026 have it slightly wrong — both have been on the list since March 2023. What moved is narrower, and more important for anyone giving goods rather than cash.
Why does the tax reference number change matter?
Because it is the field SARS matches on. Section 18A-approved organisations report the receipts they issue to SARS in third-party IT3(d) returns. SARS's own guide says the purpose is to make sure the receipt a donor claims matches what the organisation reported.
Under the 2023 notice, a receipt could leave the tax number off if the donor did not supply it. The 2026 schedule lists it without that qualifier. In practice, expect the organisation you give to to ask for your tax number before it issues the receipt — and expect that to be normal, not intrusive.
SARS's IT3(d) FAQ is plain about what happens when an organisation's reporting falls short: donors "will be subjected to an audit or other verification process" and will not get the deduction in good time — delayed refunds, for example.
What changed for donations of goods?
This is the real change. From 1 March 2026 a receipt for property donated in kind must carry an adequate and accurate description of what was given, and the deemed amount of the deduction worked out under section 18A(3) or (3A) of the Act.
That second point matters because the deductible value of goods is not simply "what it's worth". The Act deems a value, and for most goods it is the lower of fair market value or cost — not whichever is higher.
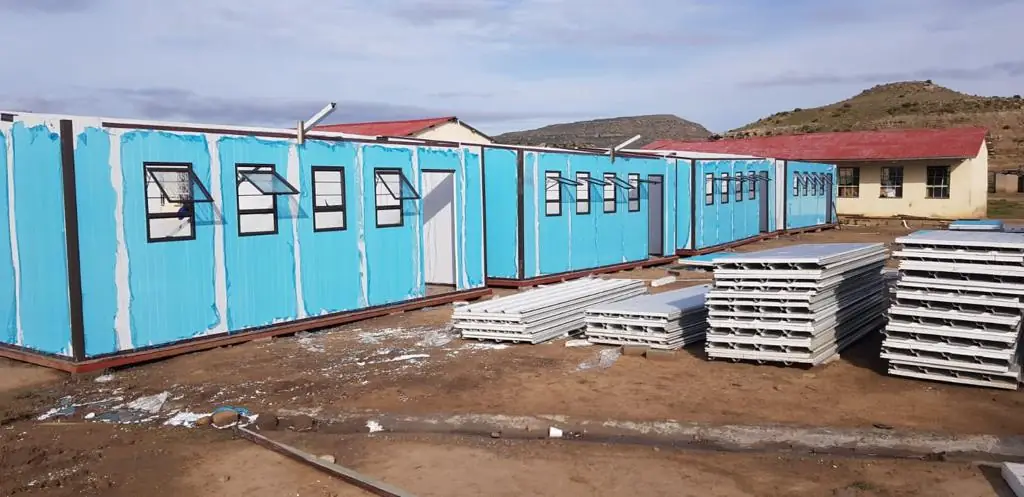
Building materials are exactly the kind of gift the new description and valuation fields are about
| What you give | Deemed deduction value |
|---|---|
| Trading stock (other than financial instruments) | The amount taken into account under section 22(8)(C) |
| An asset you used in your trade | Lower of fair market value on the date of donation, or cost less allowances claimed |
| Other property that isn't trading stock or a trade asset | Lower of fair market value, or cost (less wear-and-tear depreciation for a movable asset) |
| Property bought, made or built specifically to donate | Lower of fair market value, or cost |
| Immovable capital property where the lower of market or municipal value exceeds cost | A separate formula, under section 18A(3A) |
Two things never qualify, before or after 2026. Services — time, skill, professional work given free — are not a donation of property, so they earn no Section 18A deduction. And property subject to a usufruct or similar right is excluded.
This is general information about the Income Tax Act as it stood in September 2026. UDRS NPC is not a registered tax practitioner. Your accountant or tax advisor will apply these rules to your actual figures — especially the valuation of any goods you give.
What happens if a receipt is missing something?
The risk sits with the donor's deduction. Section 18A(2) says a claim "shall not be allowed unless supported by" a receipt containing the required details — the six in the Act, plus the further information the Commissioner prescribes by notice. Notice 6762 is that further information.
A receipt issued on or after 1 March 2026 that is still built on the 2023 template — no tax number, or a goods donation with no description or deemed value — is the receipt most likely to be questioned if SARS verifies your claim. Check it when it arrives, not when SARS asks.
What should you check on a receipt issued after 1 March 2026?
Read it against this list the day it arrives. Anything missing is far easier to fix now than during a verification.
- The organisation's Section 18A reference number, name and an address for enquiries
- The date the donation was received — which decides the tax year it falls in
- Your name, address, donor type, ID or registration details and trading name if different
- Your income tax reference number, contact number and email address
- The amount for cash; for goods, a proper description and the deemed deduction value
- The certification that it is issued for Section 18A and the donation will be used for approved purposes
- A unique receipt number
Does Notice 6762 change how much you can deduct?
No. The notice only prescribes what goes on the receipt. The deduction ceiling of 10% of taxable income, and the carry-forward of any excess to the next year, come from section 18A itself and are untouched by it. Our full Section 18A explainer walks through the 10% rule and what a donation actually costs you.
What about a receipt from UDRS?
We are not going to describe our own receipt template in a blog post — ask to see it instead. Before you commit, email info@udrs.co.za or WhatsApp us and we will show you what yours will look like against the list above.
What we ask for once you have decided to give is set out under what we need to issue the certificate — collected directly, never through a public web form. If you are planning a donation of materials or equipment, talk to us before delivery, so the description and value can be recorded properly.
Key points
- Government Notice 6762 (Gazette 53589, 24 October 2025) applies to every Section 18A receipt issued on or after 1 March 2026.
- Most fields — donor type, ID details, contact details, a unique receipt number — have been required since March 2023.
- New: the donor's income tax reference number is listed without "if available".
- New: goods donated need an accurate description and the deemed deduction value under s18A(3) or (3A) — usually the lower of market value or cost.
- The 10% ceiling is unchanged. Check every receipt against the list when it arrives.
Frequently asked questions
When did the new Section 18A receipt requirements start?
On 1 March 2026. Government Notice 6762 was published on 24 October 2025 and applies to all Section 18A receipts issued on or after 1 March 2026, the start of the 2026/2027 tax year. Receipts issued before that date were governed by Notice 3082 of 2023.
Do I have to give my tax number to get a Section 18A certificate?
Notice 6762 lists the donor's income tax reference number as required information on the receipt, without the "if available" wording the 2023 notice used. Expect the organisation to ask for it before issuing your receipt.
Is a unique receipt number a new requirement?
No. A unique receipt number has been required since 1 March 2023 under Notice 3082. Notice 6762 keeps it.
How is a donation of goods valued on a Section 18A receipt?
From 1 March 2026 the receipt must show the deemed deduction amount determined under section 18A(3) or (3A) of the Income Tax Act. For most goods that is the lower of fair market value on the date of donation or the cost to you, with specific rules for trading stock, trade assets and immovable property. Your accountant will confirm the figure for your situation.
Can I claim a Section 18A deduction for volunteering my time or services?
No. A service is not a donation of property, so time, skill or professional work given free does not qualify for a Section 18A deduction.
Did Notice 6762 change the 10% deduction limit?
No. The notice only prescribes what information a receipt must contain. The limit of 10% of taxable income, and the carry-forward of any excess to the following year, come from section 18A itself.
Want to see the receipt before you give?
UDRS NPC is an approved Public Benefit Organisation, PBO 930091096. Ask us for the approval letter and a sample receipt — you should be asking that of every organisation that offers you an 18A certificate.
Sources
Every rule above was checked against these on 27 September 2026:
- Government Notice 6762, Government Gazette No. 53589, 24 October 2025 (SARS)
- Government Notice 3082, Government Gazette No. 48104, 24 February 2023 (SARS)
- Basic Guide to Section 18A Approval, Issue 5 (SARS) — including the text of sections 18A(2) and 18A(3)
- Section 18A and IT3(d) Third Party Data (SARS)
- IT3(d) Third Party Data FAQs (SARS)