Yes. Section 18A allows a deduction for bona fide donations in cash or of property made in kind to an approved organisation, so goods qualify. Services and time do not. The deductible amount is set by section 18A(3), not by the retail price, and from 1 March 2026 the receipt must describe the goods and state that amount.
At a glance — as of October 2026
- What qualifies
- Bona fide donations in cash or of property in kind (SARS BGR 71)
- What does not
- Services, time and the use of assets — they are not property
- Amount you claim
- The amount determined under section 18A(3) or (3A), not the shelf price
- Donated trading stock
- Usually its cost or written-down value (SARS Interpretation Note 65)
- Receipt from 1 March 2026
- A description of the goods and the deemed deduction amount (Notice 6762)
- Who proves the value
- The donor, if SARS asks (BGR 71)
Can a company donate goods instead of cash under Section 18A?
Yes. SARS’s Binding General Ruling 71 describes the deduction as covering bona fide donations in cash or of property made in kind, actually paid or transferred to an approved organisation during the year of assessment. A pallet of materials is a donation in the same way a bank transfer is.
The ruling defines a donation of property in kind as anything given in a form other than cash. It excludes intangible assets, rights such as a usufruct, and most financial instruments, other than shares in a listed company or instruments issued by an eligible financial institution.
The same 10% of taxable income limit applies. SARS’s Section 18A fact sheet covers donations “in cash or in kind” under one ceiling, with anything above it carried forward to the next year of assessment.
What does not count as a donation in kind?
Services do not. A donation in kind has to transfer property to the organisation. Professional time, a free week of a tradesperson’s labour, or the loan of a truck moves no ownership, so it does not carry a Section 18A receipt, however valuable it is.
Nor does anything that brings something back to the donor. A gift must be given freely. If you receive advertising value, goods or another benefit in exchange, it is usually sponsorship, with its own tax treatment. Our Section 18A page draws the same line.
Transport, warehousing and tradespeople’s time are support our partners page asks for, and they matter. They just sit outside Section 18A. Ask your accountant how your own business should treat them.
How is the value of donated goods worked out?
Not at retail. BGR 71 says a deduction for property in kind is deemed to be the amount determined under section 18A(3), with a formula in section 18A(3A) for some immovable property. Which rule applies depends on what the goods were to you before you gave them.
For most companies giving their own stock, the answer is cost, not selling price. SARS’s Interpretation Note 65 explains that donated trading stock is valued at the amount already taken into account for it — typically cost, or written-down value where it was written down.
| What you give | Deductible amount | Source |
|---|---|---|
| Your own trading stock, e.g. cement from a supplier | The amount already taken into account for it — typically cost or written-down value | SARS IN 65 |
| A financial instrument held as trading stock | The lower of fair market value on the day and that same amount | SARS IN 65 |
| Property that is neither trading stock nor used in your trade | The lower of fair market value on the day and its cost to you, less depreciation for a worn movable asset | Income Tax Act s18A |
| Goods bought specifically to give | The lower of fair market value and what you paid | Income Tax Act s18A |
| Immovable property of a capital nature worth more than it cost | A formula in section 18A(3A) | SARS BGR 71 |
Where this matters most is the gap between cost and price. A retailer that donates stock it sells at a mark-up claims the cost, not the price tag. Your accountant applies the right paragraph to your actual figures; this table is a map, not advice.
What must the receipt show from 1 March 2026?
Two things beyond the usual details. SARS Notice 6762, published on 24 October 2025, applies to every receipt issued on or after 1 March 2026. For a donation in kind it requires an adequate and accurate description of the goods, and the deemed deduction amount under section 18A(3) or (3A).
The numbers also have to agree across three places. BGR 71 says the amount you claim must match the amount on the receipt and the amount the organisation reports to SARS in its third-party return. A receipt that says only “donated goods” leaves that chain broken.
For the full list of donor details now required, see what changed on Section 18A certificates from 1 March 2026.
Why speak to the organisation before the delivery arrives?
Because the paperwork is built on agreed facts. The receipt needs a description and an amount, and the organisation has to report it. Settling what is being given, how many, and the basis of the figure before it is offloaded is far easier than reconstructing it afterwards.
The burden of proof sits with the donor. BGR 71 notes that SARS may ask for evidence supporting the deemed amount, and that the donor must substantiate it on assessment. Keep invoices, stock records or a valuation with the receipt.
It is also practical. Goods are only useful if they fit the work and can be stored and moved. That is why our Section 18A page says it plainly: talk to us before delivery.
What goods are actually useful to UDRS?
The ones our programmes already use. Our Section 18A page names materials, vehicles, food and equipment, and the partners page names building materials. In-kind support goes far here because it removes cost we would otherwise fundraise for.
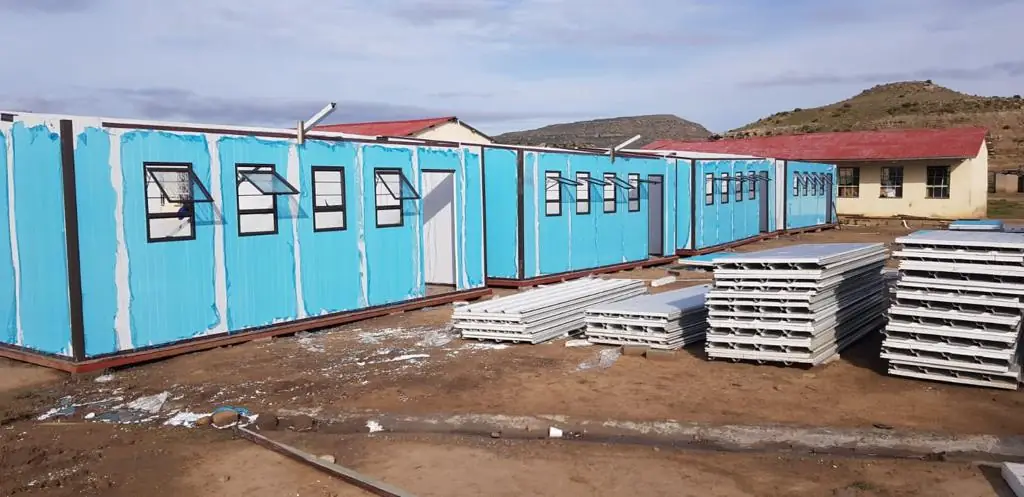
- Building materials for the housing work, which is a pilot in Kya Sand: built, placed and lived in, with costing the repeatable version as the next step.
- Food for the soup kitchens and relief distributions.
- Equipment and vehicles, because units, materials and relief loads have to physically arrive.
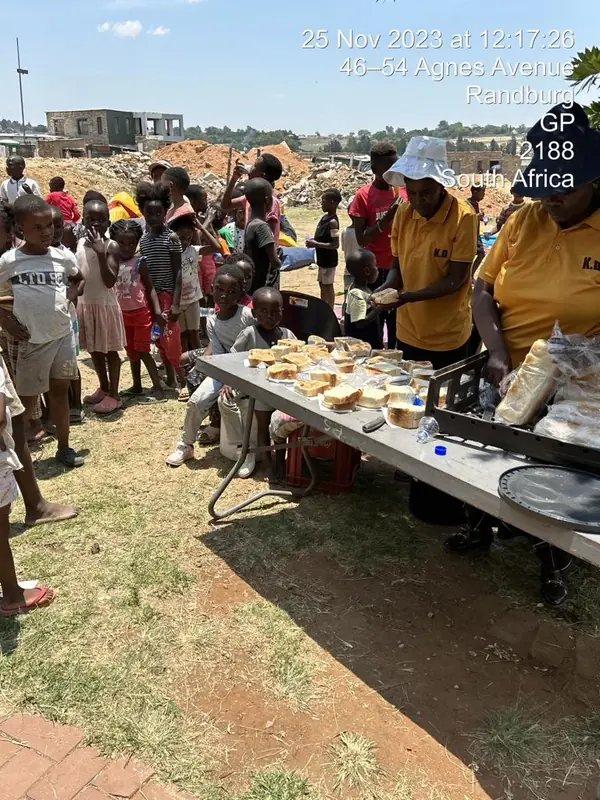
Food served at a UDRS feeding day — one of the places donated food goes
This page explains the rules as of October 2026. It is not tax advice, and UDRS NPC is not a tax practitioner. Your accountant will apply this against your actual figures.
Key points
- Goods qualify for Section 18A. Services and time do not.
- The deduction is the section 18A(3) amount — for your own stock, usually cost, not selling price.
- From 1 March 2026 the receipt must carry a description and the deemed amount.
- The donor carries the burden of proof, so agree the details before delivery.
Frequently asked questions
Can a company donate goods instead of cash under Section 18A?
Yes. Section 18A covers bona fide donations in cash or of property made in kind to an approved organisation. Building materials, food, equipment and vehicles can all qualify, within the same 10% of taxable income limit that applies to cash.
Do donated services qualify for Section 18A?
No. A donation in kind must transfer property to the organisation. Professional time, labour or the use of an asset transfers no property, so it cannot carry a Section 18A receipt. Ask your accountant how your business should treat donated services.
Is the deduction the retail value of the goods?
Usually not. The deduction is the amount determined under section 18A(3). For a company’s own trading stock that is typically cost or written-down value. For other property it is generally the lower of fair market value and cost.
What must a Section 18A receipt show for a donation in kind?
From 1 March 2026, SARS Notice 6762 requires an adequate and accurate description of the goods and the deemed amount of the deduction under section 18A(3) or (3A), alongside the donor’s details and a unique receipt number.
Who has to prove the value of donated goods?
The donor. SARS’s Binding General Ruling 71 says SARS may ask for evidence supporting the deemed amount, and the donor must substantiate it on assessment. Keep invoices, stock records or a valuation with the receipt.
Does the 10% limit apply to donations in kind?
Yes. SARS applies the same 10% of taxable income limit to donations in cash or in kind. Any amount above the limit is carried forward and treated as a donation in the following year of assessment.
Have goods to give?
UDRS NPC is an approved Public Benefit Organisation, PBO 930091096. Tell us what you have before it ships, and we will tell you whether it fits the work and what we need to receipt it properly.
Prefer email or a call? Our contact page has every route. For the cash side, read how much a company can deduct under Section 18A.
Sources
Checked on 21 October 2026:
- Binding General Ruling 71: Section 18A receipt — donation of property in kind (SARS, 16 May 2024) — what counts as property in kind, section 18A(3)/(3A), matching amounts, burden of proof
- Notice 6762, Government Gazette 53589 (SARS, 24 October 2025) — receipt details for donations in kind from 1 March 2026
- Interpretation Note 65, Issue 3 (SARS, 6 February 2017) — valuing donated trading stock
- Section 18A fact sheet (SARS) — cash or in kind under the 10% limit, and the carry-forward
- Income Tax Act, section 18A text (SAIT Compendium 2016, Juta) — the lower-of-value-and-cost rule for other property; confirm current wording with your accountant
- Donations in kind and Section 18A certificates (Accounting Weekly) — services, time and the use of assets do not qualify